
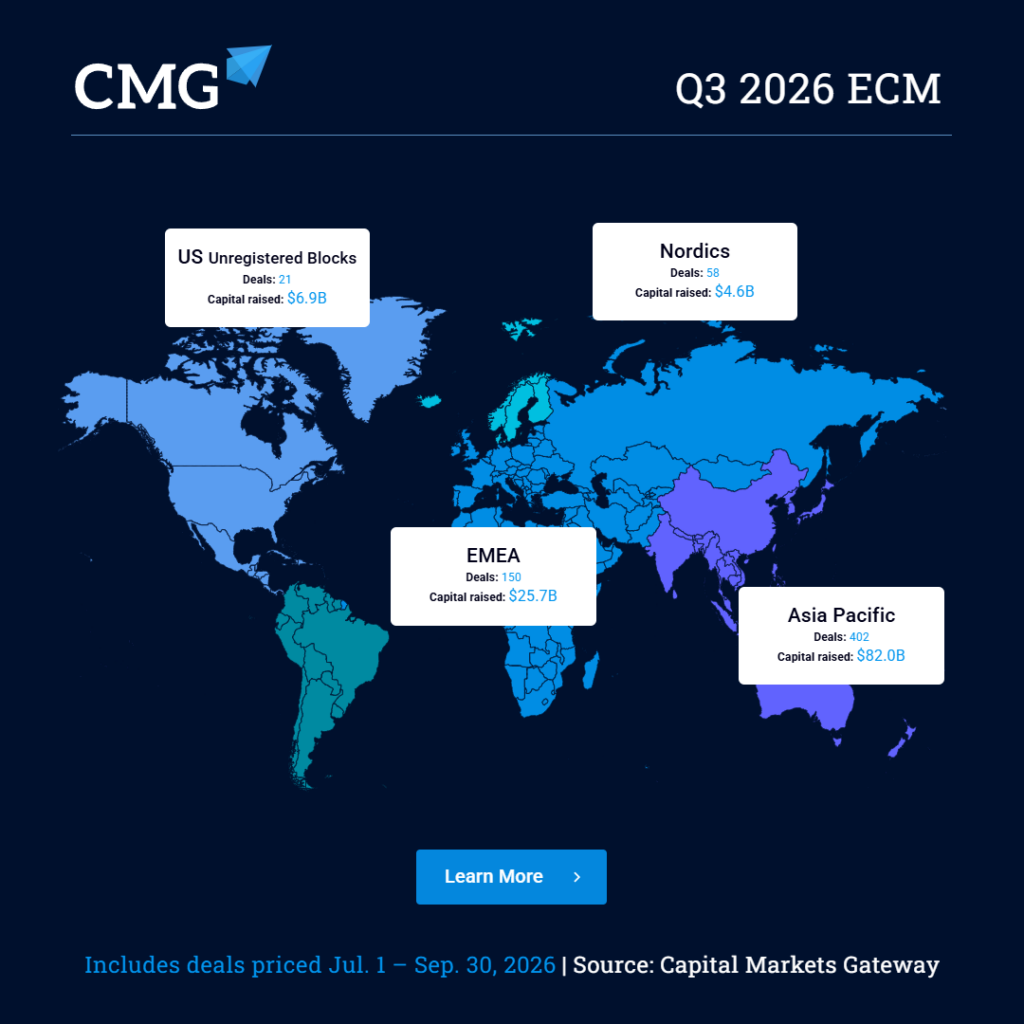
Q3 2026 was a quarter of divergence for global equity capital markets. APAC posted its most prolific third quarter for capital raised since 2020, while EMEA, the Nordics and US unregistered blocks all cooled after a busy Q2.
From Zhongji Innolight’s $7.8B Hong Kong IPO to the largest unregistered block ever seen out of Norway, the quarter still delivered standout deals, even as the gap between regions widened.
For more key data points and trends that defined the third quarter, download CMG’s Q3 2026 Global ECM Recap.
Key Takeaways
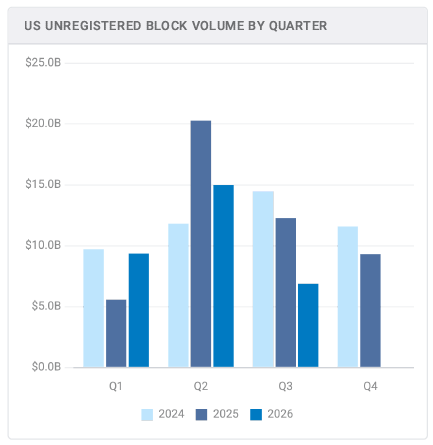
Capital raising concentrated in APAC this quarter. APAC raised $82.0B, up 63% over Q2, while EMEA ($25.7B), the Nordics ($4.6B) and US unregistered blocks ($6.9B) all fell 30% or more quarter over quarter.
Technology led the way where volume held up, driving $32.4B in APAC and $6.7B in EMEA. Aftermarket performance softened everywhere: average offer-to-1-day returns for IPOs fell below FY25 levels in APAC, EMEA and the Nordics, and US unregistered blocks traded down on average.
In H1, the regions with the strongest returns weren’t the ones with the strongest volume growth. In Q3, even the region with the strongest volume saw returns cool, a sign that issuers are still finding demand but investors are pricing it more carefully.
Here’s a detailed breakdown of how APAC, EMEA, the Nordics and US unregistered blocks each shaped up in the third quarter.
APAC
402 deals • $82.0B raised
APAC continued its strong year, with Q3 2026 its most prolific third quarter for capital raised since 2020.
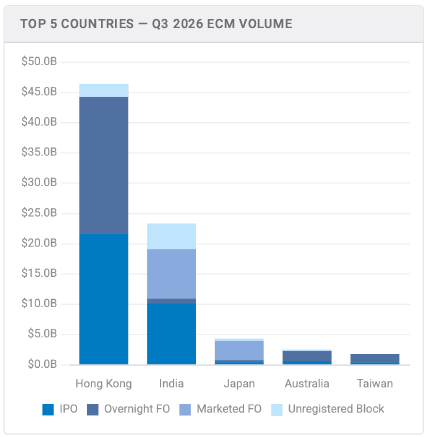
- Largest deal: Alibaba Group raised $10.2B in an overnight follow-on in Hong Kong
- Largest IPO: Zhongji Innolight raised $7.8B in Hong Kong, one of the largest A-H IPOs ever
- Another notable deal: National Stock Exchange of India raised $2.4B in its September IPO, the fifth largest Indian IPO ever
Hong Kong was the engine behind APAC’s quarter, leading the region by country volume and accounting for seven of its ten largest deals. Technology issuers drove much of that, from Zhongji Innolight and Luxshare Precision ($3.2B) to two overnight follow-ons from Z.AI totaling $6.0B.
India was the region’s second-largest market, anchored by Life Insurance Corp. of India’s $3.3B marketed follow-on, NSE’s IPO and Adani Enterprises’ $1.6B marketed follow-on. APAC IPO volume in Q3 was the highest of any quarter since the start of 2024, but a cooler aftermarket suggests investors were more selective about what they paid for that supply.
EMEA
150 deals • $25.7B raised
EMEA capital raised declines compared to both the previous quarter (Q2 2026) and the same period last year (Q3 2025), even as deal count rose year over year.
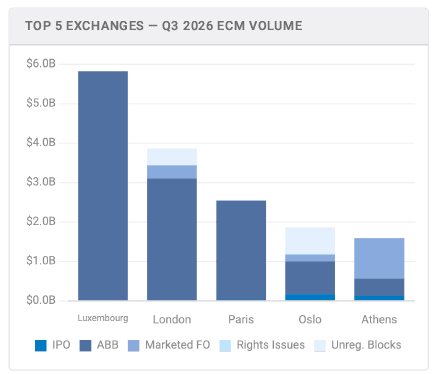
- Largest deal: Quanta Computer raised $2.2B in a 100% primary ABB via GDSs in Luxembourg
- Largest IPO: Oman India Fertilizer Company (OMIFCO) raised $679M in Muscat
EMEA’s quarter was defined by accelerated bookbuilds. Eight of the region’s ten largest deals were ABBs, led by a run of GDS offerings in Luxembourg from Quanta Computer, Wistron ($1.5B) and GlobalWafers ($1.4B). Those three deals made Luxembourg EMEA’s busiest exchange and explain technology’s jump to the top of the sector rankings.
With deal count up 36% year over year but proceeds down 17%, EMEA issuers came to market more often in smaller sizes, a trend mirrored in an average IPO size that nearly halved from Q2.
Nordics
58 deals • $4.6B raised
The Nordics have had a strong 2026 so far. Q3 proceeds fell from Q2, but capital raised was up 84% on Q3 2025 and deal count doubled.
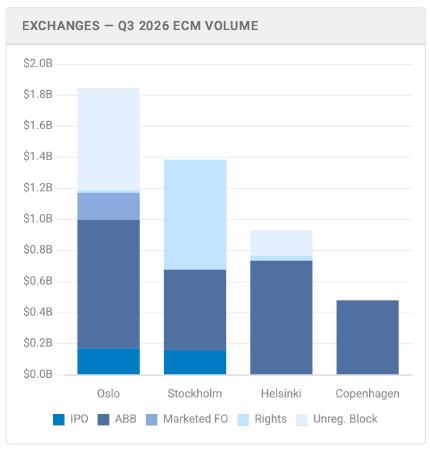
- Largest deal: Sampo raised $722M in an ABB in Helsinki
- Largest rights issue: Intrum raised $589M in Stockholm
- Another notable deal: Aker BP’s $524M unregistered block in Oslo, the largest ever out of Norway
Oslo was the region’s busiest exchange, with unregistered blocks making up a meaningful share of its volume alongside ABBs from Hafnia ($300M), AutoStore ($174M) and Höegh Autoliners ($152M). Rights issues remained a key financing tool, though their aftermarket performance fell to roughly half of FY25 levels.
U.S. Unregistered Blocks
21 deals • $6.9B raised
Q3 2026 saw fewer unregistered blocks and less capital raised than both Q2 2026 and Q3 2025, making it the lightest quarter of the year so far.
- Largest deal: Diamondback Energy raised $1.9B in September
- Clean-up trades: Two of the 21 blocks allowed a shareholder to fully exit their position
- Leading sector YTD: Energy has led US unregistered block volume across Q1 to Q3 2026
Block sizes have generally trended larger in 2026. With seven $1B+ blocks already priced, this year is within reach of FY25’s full-year total, even as overall volume slowed in Q3.
As Q4 gets underway, the key question is whether APAC’s momentum carries into year end, and whether softer aftermarket returns weigh on issuance in EMEA, the Nordics and the US block market.
